This article analyzes the market share, market size, and mergers and acquisitions (M&A) of the HVAC industry in North America. Growth in the North American HVAC market is being led by commercial demand, which is more than offsetting continued weakness in the residential segment.
The article also provides an overview of the North American HVAC market and its major players—Trane
Technologies, Daikin, Carrier Global, Johnson Controls, Lennox, and others—as well as a range of operating and financial metrics.
Scope of the HVAC Market
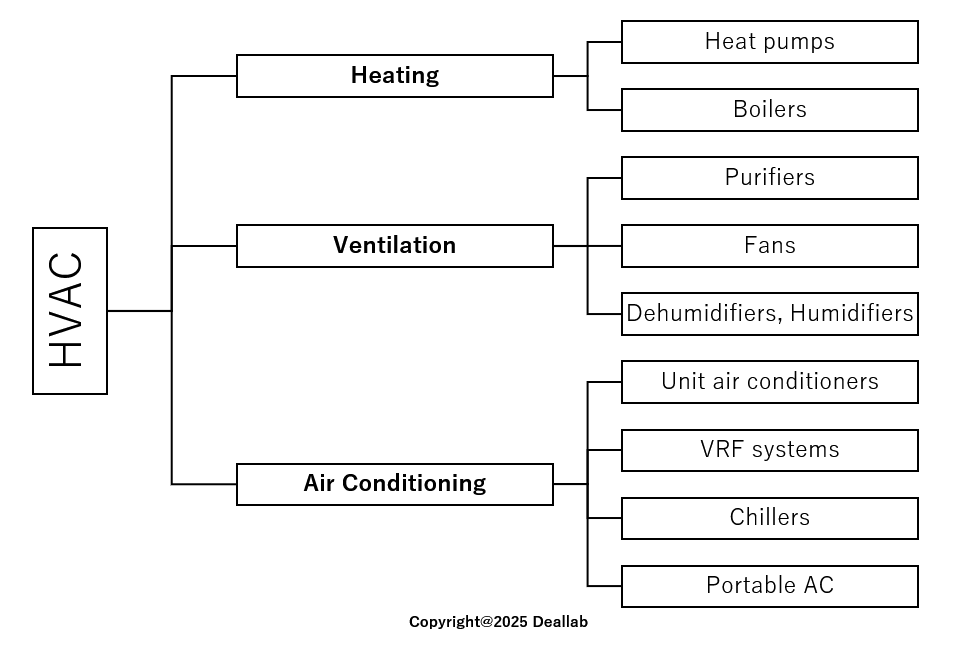
HVAC stands for heating, ventilation and air conditioning. Broadly speaking, the HVAC market can be divided into two categories: (1) the equipment business, which manufactures and sells heating, ventilation, and cooling equipment; and (2) the solutions business, which provides maintenance and services related to HVAC systems.
In recent years, the solutions business has been expanding as interest grows in energy management and
energy efficiency across entire facilities, and as owners and operators increasingly seek integrated HVAC
systems from an operations and maintenance standpoint.
Heating, ventilation, and cooling equipment can be further segmented into heat pumps, boilers, air purifiers, ventilation fans, dehumidifiers and humidifiers, unitary air conditioners, VRF systems, chillers, portable air conditioners, and other products.
Market Share of the North American HVAC Industry
Based on estimated 2025 North American HVAC revenue and the market-size estimate presented below,
Trane Technologies ranked first, followed by Daikin, Carrier Global, Johnson Controls and Lennox.
Note: For Johnson Controls, sales for the fiscal year from October 2024 through September 2025 were used.
| Ranking | Company | Market Share |
|---|---|---|
| No. 1 | Trane Technology plc | 24.39% |
| No. 2 | Daikin Industries, Ltd. | 19.41% |
| No. 3 | Carrier Global Corporation | 17.30% |
| No. 4 | Johnson Controls, Inc. | 14.18% |
| No. 5 | Lennox International Inc. | 8.10% |
North America HVAC market shares (2025)
Source: Deallab estimates based on each company’s annual reports and other materials for fiscal 2025.

The two halves of the market have moved in opposite directions. On the commercial side, capital spending has been strong, supported by data-centre construction, and by efficiency upgrades in offices, hospitals and educational buildings. Tax credits and incentives under the Inflation Reduction Act have supported high efficiency and electrification projects in the United States. Residential demand has been softer: new home activity has been held back by high mortgage rates and elevated prices, leaving replacement demand — driven by efficiency standards and the refrigerant transition — as the main support.
That split shows up in company results. Trane Technologies, whose strengths lie in applied systems for data
centres and large commercial facilities, has benefited most directly from commercial capital spending.
Daikin, with a heavier residential weighting in North America through Goodman, has relied more on
replacement demand. In Deallab’s assessment, part of the year-on-year movement in reported shares also
reflects currency translation, since Daikin reports in yen.
Size of the North American HVAC Market
Based on NextMSC’s estimate of the global HVAC market and North America’s regional share, Deallab estimates the North American market at approximately $57.9 billion in 2025.
| Year | Market size | Growth Rate |
|---|---|---|
| 2025 | $57.9 billion | 4.88% |
| 2034 | $99.5 billion | 6.20% |
The 2025 figure is derived by applying North America’s regional share to NextMSC’s global market estimate. The year-on-year growth rate is calculated against the equivalent 2024 figure; the 2034 figure is a compound annual growth rate over the full 2025–2034 period. The two are not comparable measures.
The research data referenced are as follows. Fortune Business Insights estimates the industry’s 2025 market size at approximately USD 51.6 billion and projects it to expand to roughly USD 75.8 billion by 2032.
NextMSC estimates the global HVAC market at approximately USD 236.1 billion in 2025, with North America accounting for 24.53%. It projects the global market to expand to about USD 430.9 billion by 2035.
The North American HVAC market is expected to continue growing, supported by increased cooling demand due to hotter summers and by the replacement and renewal of installed equipment.
One factor supporting replacement demand is SEER2, the new standard for evaluating air-conditioner energy efficiency. Because SEER2 evaluates efficiency under conditions closer to actual usage than the previous standard, replacement with high-efficiency models that meet the new requirements is advancing.
Stricter environmental regulations are also encouraging replacement demand. Beginning in 2025, the United States prohibited the manufacture and import of certain new HVAC equipment using R410A, a refrigerant with a high global warming potential (GWP). This is expected to accelerate the shift toward equipment using lower GWP refrigerants such as R32, used by Daikin, and R454B, used by Carrier and Johnson Controls, thereby supporting replacement demand for installed systems.
Growth in the data-center market is also expected to drive HVAC expansion. Data centers contain large
numbers of servers, which generate substantial heat while operating. Stable operation therefore requires
temperature control using high-performance HVAC equipment and cooling systems. Every new or expanded data center creates additional investment in cooling and air-conditioning equipment, making data centers a major source of HVAC demand.
According to Mordor Intelligence, the North American data-center market is projected to grow at a CAGR of 10.49% between 2025 and 2030, reaching USD 25.3 billion by 2030. This expansion is being driven by rising cloud demand and the rapid development of AI. AI servers are said to consume several times—and in some cases more than ten times—the electricity of ordinary cloud servers, requiring higher cooling capacity. Temperature control is also a technologically demanding field, making it an area in which manufacturers are expected to continue innovating.
North America in the Global Market
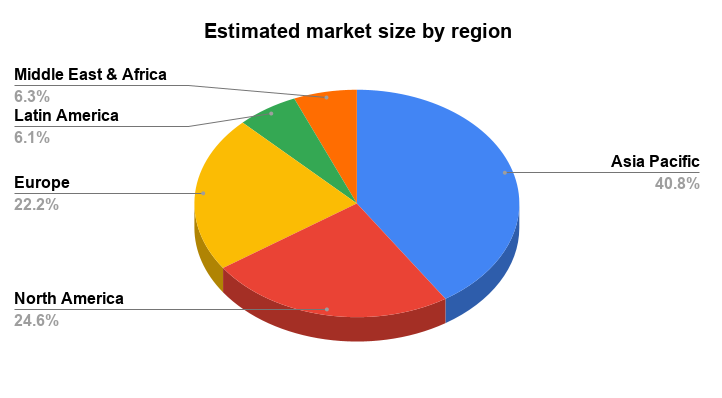
According to NextMSC, Asia-Pacific is the largest HVAC market, accounting for roughly 40% of the global total. North America represents close to one quarter of the worldwide market, underscoring its importance.
Analysis of Major North American Companies
Comparison of Revenue Mix
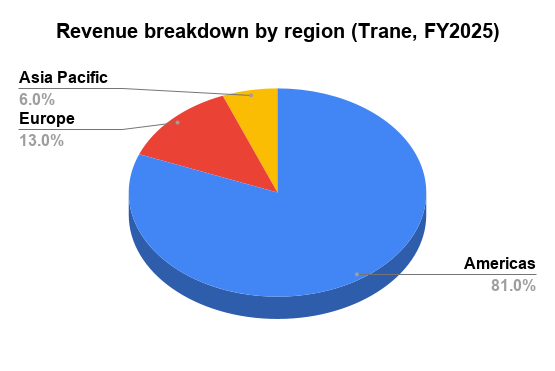
A comparison of revenue by region shows that market leader Trane Technologies has a high proportion of
sales in North America and Latin America. Daikin also derives a large share of sales from the United States, the world’s largest national market, but is distinguished by a more balanced presence across China, Japan, and Europe.
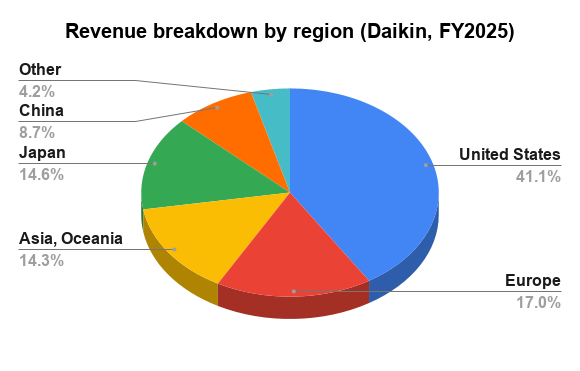
HVAC has traditionally been regarded as a difficult industry in which to expand globally because consumer needs and dominant technologies—such as ducted and ductless systems—vary by region. Daikin was an early mover in overcoming this challenge and building a successful international business.
In North America, Daikin expanded its business platform through acquisitions including McQuay in 2008 and Goodman in 2012, creating a broad product lineup spanning residential through commercial applications. The expansion of its North American operations has contributed substantially to growth in Daikin’s overall performance and enterprise value, including market capitalization.
Approximately 30 years ago, overseas sales accounted for around 15% of Daikin’s total revenue. By 2025, the ratio had risen above 85%. More recently, Daikin has been expanding production capacity and strengthening sales operations in Southeast Asia, the Middle East, Africa, and India.
- 2022: Established an air-conditioner manufacturing plant in Indonesia.
- 2022: Established its second assembly plant in the Middle East, in Saudi Arabia.
- 2023: Began construction of a new heat-pump heating plant in Poland.
- 2023: Established an air-conditioning sales company in Cambodia.
- 2023: Opened a new air-conditioner production base in India.
- 2024: Built a residential air-conditioning production network in Africa.
- 2024: Established a joint venture with leading Taiwanese HVAC company Rechi and other partners.
- 2025: Established a new HVAC equipment plant in Saudi Arabia.
In recent years, other companies have also accelerated international expansion, following the global strategy Daikin pioneered. In November 2022, Trane Technologies completed its acquisition of major German HVAC manufacturer AL-KO Air Technology. It acquired Italy’s MTA in May 2023 and has continued to pursue growth outside North America.
In 2024, Carrier Global acquired Germany’s Viessmann Climate Solutions. The accelerating international
expansion of competitors after Daikin is becoming increasingly evident.
M&A Trends Among Major North American Companies
Recent M&A activity has increasingly extended beyond direct acquisitions of HVAC equipment businesses.
More transactions are aimed at adding value to conventional HVAC functions by optimizing energy efficiency across entire buildings.
For example, Daikin’s 2022 acquisition of Venstar enabled it to offer remote HVAC services. Trane
Technologies’ acquisitions of Nuvolo and BrainBox AI were intended to enhance building and facility
management solutions and strengthen the creation of new customer relationships.
In 2025, Johnson Controls sold its residential and light-commercial HVAC business to Bosch in order to focus on building solutions. This suggests that major restructuring of the global industry is likely to continue.
Major M&A Projects
- 1979: United Technologies acquired Carrier.
- 2006: Daikin acquired Malaysian HVAC manufacturer OYL.
- 2008: Ingersoll-Rand acquired Trane.
- 2011: Midea Group acquired Carrier’s South American business.
- 2012: Daikin acquired Goodman Global.
- 2014: Johnson Controls acquired U.S.-based Air Distribution Technologies.
- 2016: Johnson Controls merged with Tyco.
- 2016: Daikin acquired U.S.-based Flanders.
- 2018: Johnson Controls acquired airflow-solutions manufacturer Triatek.
- 2018: Mitsubishi Electric and Ingersoll-Rand established a joint venture to sell ductless HVAC systems.
- 2020: Ingersoll-Rand spun off Trane Technologies.
- 2020: Daikin acquired HVAC distributors ABCO, Robinson, and Stevens.
- 2020: United Technologies spun off Carrier.
- 2021: Carrier, together with major U.S. HVAC distributor Watsco, acquired Temperature Equipment
Corporation (TEC). - 2021: Johnson Controls acquired U.K.-based HVAC sales and installation company Fisher Group.
- 2021: Daikin acquired HVAC wholesaler Thermal Supply and commercial HVAC distributor AirReps.
- 2022: Carrier made Toshiba Carrier a subsidiary through its subsidiary Global Comfort Solutions LLC.
- 2022: Johnson Controls acquired AI software company FogHorn.
- 2022: Daikin acquired U.S. controls and communications company Venstar.
- 2022: Trane Technologies acquired major German HVAC company AL-KO.
- 2023: Trane Technologies acquired Italy’s MTA.
- 2023: Daikin acquired U.S.-based Alliance Air Products and CM3 Building Solutions.
- 2023: Lennox acquired U.S. commercial HVAC service company AES.
- 2023: Trane Technologies acquired U.S. facility-management solutions provider Nuvolo.
- 2023: Carrier sold its commercial refrigeration division to Chinese partner Haier.
- 2023: Lennox announced plans to sell its European HVAC business to an investment fund.
- 2024: Carrier acquired Germany’s Viessmann Climate Solutions.
- 2024: Lennox and Samsung agreed to establish a joint venture.
- 2024: Daikin acquired U.K.-based Robert Heath Heating.
- 2024: Trane Technologies acquired distributor Damuth Services.
- 2025: Carrier acquired Portuguese company Addvolt.
- 2025: Trane Technologies acquired BrainBox AI, which develops AI-based HVAC controls.
- 2025: Bosch acquired Johnson Controls’ residential and light-commercial HVAC business.
In the North American HVAC market, companies are strengthening their businesses and expanding share
through M&A while also achieving organic growth. At the same time, some players are concentrating on largescale equipment within the broader HVAC business. Industry consolidation in North America is therefore expected to accelerate further through continued M&A.
Comparison of Key Metrics for the North American HVAC Big Three
The table below compares five-year revenue CAGR, dividend payout ratio, and return on equity (ROE) for three major North American HVAC companies: Trane Technologies, Daikin, and Carrier. Daikin leads in revenue growth, Carrier in dividend payout ratio, and Trane Technologies in ROE.
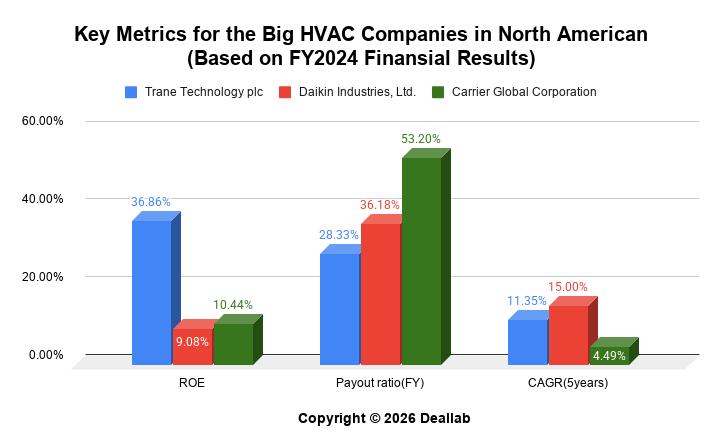
Dividend payout ratios are calculated on a trailing-twelve-month basis as of 16 July 2026. ROE uses net
income for the latest fiscal year over the average of opening and closing shareholders’ equity. Revenue growth is the compound annual rate over the past five fiscal years. Market-share estimates elsewhere in this article are based on fiscal 2025 results; valuation and shareholder-return metrics in this table were updated as of 16 July 2026.
Daikin has the highest five-year revenue growth rate at 15.00%, reflecting expansion in business scale
supported by aggressive overseas development and demand growth. Trane Technologies follows at 11.35%, benefiting from rising HVAC demand from AI data centers and large commercial facilities. Carrier’s 4.49% is solid, but more moderate than the other two.
Carrier has the highest dividend payout ratio at 53.20%, indicating an active stance toward returning profits to shareholders. Trane’s 28.33% is relatively low, leaving more room to allocate earnings to growth investment and share repurchases. Daikin’s 36.18% lies between the two and suggests a capital policy that balances growth investment with shareholder returns.
Trane Technologies’ ROE of 36.86% is far above the other two companies. This reflects a higher weighting of profitable commercial HVAC and service businesses, as well as improved capital efficiency through measures such as share repurchases. Daikin and Carrier are both around 10%, indicating stable profitability, while Trane stands out in capital efficiency.
Company Profiles
Daikin
Daikin is a leading Japanese HVAC manufacturer established in 1924. It is one of the world’s top companies in industrial heating, ventilation, and air-conditioning equipment. It has expanded globally through acquisitions including U.S.-based Goodman, which is strong in ducted systems, and Malaysia’s OYL. In Japan, it competes with Panasonic in residential air conditioners. Daikin also operates a chemicals business, including fluorochemical products.
Carrier Global
Carrier Global is a major U.S.-based heating, ventilation, and air-conditioning manufacturer. It was formerly a subsidiary of United Technologies, a major company also active in aircraft engines and elevators. In 2020, United Technologies separated into Carrier Global for HVAC, Otis for elevators, and an aerospace components business. In addition to HVAC, Carrier has strengths in transport refrigeration equipment and fire-alarm systems.
Johnson Controls (York International Corporation)
Johnson Controls, founded in 1885 and headquartered in the United States, provides commercial HVAC
control systems, security systems, fire-detection systems, and building-management services. It has a
historical connection to the invention of the electric thermostat. In 2016, it merged with Tyco International,
which was strong in fire-alarm systems. The company operates in 150 countries and provides energy efficiency solutions and various automation services. It was formerly strong in automotive batteries but sold that business in 2018. In 2025, it sold its residential and light-commercial HVAC business to Bosch.
Trane Technologies
Trane Technologies is a U.S.-based manufacturer of industrial heating, ventilation, and air-conditioning
equipment. It was formerly part of Ingersoll-Rand, a U.S. company involved in transport temperature-control equipment, golf carts, air compressors, and other products, and was spun off as an independent company under the Trane Technologies name in 2020. Before its period under Ingersoll-Rand, it was also part of American Standard, which manufactured products including sanitary ware.
Ingersoll-Rand
Ingersoll-Rand is a U.S.-based industrial equipment manufacturer founded in 1871. In 2020, it merged with
Gardner Denver, a manufacturer of industrial machinery such as vacuum pumps and compressors. Before the merger, its HVAC business was spun off as Trane Technologies. Over the years, leading companies in various fields have emerged from Ingersoll-Rand, including lock manufacturer Allegion and refrigerated-display-case maker Hussmann, which was sold to Panasonic in 2015. The company is also strong in compressors, air tools, and transport refrigeration. It developed the Club Car golf-cart brand into one of the world’s largest businesses in the field before selling it to Platinum Equity in 2021.
Lennox International
Lennox International is a U.S.-based heating, ventilation, and air-conditioning manufacturer founded in 1895. It has strengths in residential and industrial HVAC and in commercial refrigeration. Its refrigeration products include unit coolers, fluid coolers, air-cooled condensers, air handlers, and refrigerated rack systems supplied to supermarkets, convenience stores, restaurants, warehouses, and distribution centers.


